The unseen mechanics of Niamey’s uranium strategy
When Niger’s military leaders severed ties with Orano, the French nuclear giant that had extracted the country’s uranium for over fifty years, they promised a new era of sovereignty and better returns. Behind the dramatic headlines, however, a more complex reality has taken shape. Since the July 2023 coup, Niamey has nationalised the Somaïr mining company, revoked Orano’s permit for the massive Imouraren deposit, and courted a diverse array of new partners—from Russia and China to Iran and, more recently, Western investors. The goal is clear: regain control over a strategic resource and sell it on more favourable terms. Yet, as the dust settles, a fundamental question persists: is Niger actually getting a better deal today than it did under Orano? The available evidence suggests a nuanced answer. Niamey’s bargaining power has undoubtedly grown, but no public data confirms that the country is consistently securing higher prices. More troubling still, several confidential negotiations have been reported, though no secret contract has been irrefutably established.
The Orano divorce: sovereignty gained, industry weakened
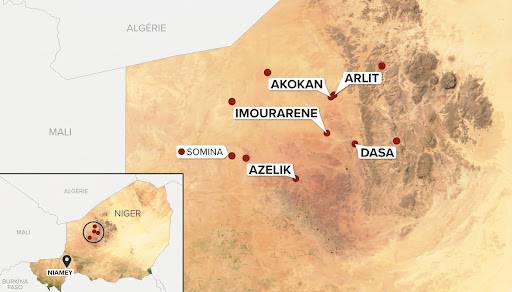
The split between Niamey and Orano is not merely diplomatic—it is industrial and financial. Orano lost operational control of its Nigerien operations in December 2024, and the Somaïr, the historic operator of the Arlit mine, was nationalised on 19 June 2025. The French group, which held 63.4% of Somaïr against the Nigerien state’s 36.6%, contests the nationalisation and has launched multiple international arbitration proceedings.
The problem for Niamey is that taking over a mine does not automatically guarantee a market. Niger’s production has fallen sharply over the past decade, from 4,116 tonnes in 2015 to just 962 tonnes in 2024, according to data reported in 2026. The country now has only one operational mine, while several projects remain undeveloped. In other words, mining sovereignty has advanced faster than the country’s industrial and commercial capacity.
The uranium price: avoiding a false accusation against Orano
A widespread misconception compares the supposed “French price” with the current global price. That comparison is misleading. Uranium does not function like oil: there is no single stock exchange setting a daily price at which all producers sell. Contracts are negotiated directly between producers, intermediaries, and nuclear utilities, with formulas that may incorporate spot and long-term indices.
Historical data nonetheless offers an interesting benchmark. In 2020, available figures indicated that Niger received about 48.1 billion CFA francs for 1,113 tonnes from Cominak and 103.3 billion CFA francs for 1,879 tonnes from Somaïr. For Somaïr, that equated to roughly €83.75 per kilogram of uranium, based on calculations from public data at the time. Another analysis using EITI data estimated that uranium purchased from Orano in recent years was around 45,000 CFA francs per kilogram, or about $33 per pound, while some European or Japanese buyers reportedly paid around 60,000 CFA/kg.
The market has since shifted considerably. In 2025, the average spot price paid by European utilities was $70.33 per pound, up from $53.59 in 2024. The average price of multi-year contracts, however, was much lower, at $54.70 per pound. By late September 2026, the spot indicator stood around $89.63/lb, while the long-term price reached approximately $96.50/lb. The conclusion is significant: Niger now operates in a far more favourable price environment than in the early 2020s. But that does not prove Niamey is actually selling its uranium at $90 or $100 per pound. This is where the file becomes opaque.
The mysterious $170 million Russian contract
The most spectacular case concerns the yellowcake stockpile accumulated at Arlit. In 2025, several French sources claimed that Niamey had struck a deal with Russia for 1,000 tonnes of uranium concentrate for about $170 million. If confirmed, that would equate to roughly $170 per kilogram, or nearly $77 per pound. That price would be below the spot price of late September 2026 but comparable to certain contractual levels seen on the international market.
The problem is that the agreement has never been officially confirmed by either party. The Nigerien government denied selling the stock, and Rosatom stated it was not party to the alleged deal. Yet the affair is not merely a rumour without material elements. In November 2025, about 1,000 tonnes of yellowcake were indeed loaded onto trucks at Arlit. Around thirty vehicles then headed to Niamey under military escort. The convoy ultimately became stranded at the capital’s airport. This is precisely where the grey zone begins. A physical transfer of such magnitude does not, by itself, prove a sale. But it demonstrates that Nigerien authorities were actively working to commercialise the stock. The $170 million figure must therefore be presented as an allegation documented by several sources, not as an established contract.
Iran: confidential talks that left traces
The Russian case is not the first opaque episode. In 2024, Le Monde revealed confidential negotiations between Niamey and Tehran over 300 tonnes of yellowcake, valued at an estimated $56 million. Several Western and Nigerien sources confirmed the existence of discussions. The Nigerien government, however, denied concluding a sale. An adviser to the junta nevertheless acknowledged that Iran had wanted to buy the 300 tonnes, explaining that Niamey refused due to a lack of available stock.
Again, three notions must be distinguished: negotiation, agreement, and executed contract. The available information establishes the existence of negotiations. It does not prove that a clandestine delivery took place.
Russia and China: new allies or new clients?
Russia is now Niamey’s most visible geopolitical partner in the nuclear sector. In December 2025, the Nigerien company Timersoi National Uranium Company signed a cooperation agreement with Uranium One Group, a subsidiary of Russia’s Rosatom, to explore deposits and eventually develop new mines. China, too, has shown interest in the Arlit stocks. In 2025, sources reported discussions potentially involving around 1,000 tonnes. But these new partners do not necessarily guarantee better prices. They primarily offer Niger more negotiating options. That is a fundamental difference.
Is Niger really selling its uranium for more today?
At this stage, the most honest answer is: not yet demonstrated. Niger now has three advantages it did not possess with the same intensity before. First, the international uranium price is much higher. Second, Niamey is seeking to diversify its partners: Russia, China, but also Canadian, Australian, and American actors. Third, the government now directly controls a key part of the mining chain.
But three weaknesses limit this strategy: falling production, logistical problems, and legal uncertainty linked to the dispute with Orano. In September 2025, an ICSID arbitral tribunal ordered Niger not to sell or transfer to third parties the uranium produced by Somaïr that is subject to the litigation. Political sovereignty alone is therefore not enough to create a solvent market.
The Nigerien paradox
Niger now wants to sell its uranium “at the best price.” But to achieve that, it must be able to produce regularly, transport its ore safely, attract capital, and legally guarantee its contracts. The country is precisely trying to rebuild that capacity. In 2026, it even created the Teloua Safeguarding Uranium Mining Company, intended to replace the nationalised Somaïr. Meanwhile, new Western investors are returning: in September 2026, the United States approved up to $414 million in financing for Global Atomic’s Dasa project, led by a Canadian company. This may be the real turning point.
Niger is not simply replacing France with Russia. It is gradually trying to turn its uranium into a lever for competition among several powers. For now, however, no public evidence allows the assertion that new contracts bring more to Niger than those concluded under Orano. International price levels are higher, yes. Negotiating possibilities are more numerous, yes. But the contracts actually signed, their price formulas, premiums, logistical costs, and the net share returning to the state remain largely opaque.
As for “secret contracts,” there are confidential negotiations and accusations serious enough to justify investigations, particularly around Iran and Russia. But to speak of definitively established secret contracts would, to date, go beyond the available evidence. The real issue for Niamey is therefore no longer just knowing whom to sell its uranium to. It is knowing at what price, with what guarantees, and above all, what share of that value will actually remain in Niger.
Comments are closed, but trackbacks and pingbacks are open.